Stop Losing Time on Buyer Leads Who Aren't Pre-Approved
By Mac McKee, QLFI ·
Quick answer
When buyer leads are not pre-approved, agents risk spending unpaid time showing homes to clients who cannot secure financing. To prevent this, integrate a digital pre-qualification step into your lead capture process, confirming their preliminary buying power before scheduling property tours.
Key takeaways
- Unverified buyer leads consume valuable time that could be spent on ready buyers.
- Requesting a preliminary credit estimate upfront sets clear expectations.
- Digital platforms verify identity and estimate buying power using soft credit inquiries.
- Refusal to authorize an inquiry does not inherently mean a buyer is financially unqualified.
The Cost of Showing Homes Without Pre-Approval
Real estate agents often hesitate to ask new buyer leads for financial details to avoid creating friction.
However, showing properties to buyers who have not spoken to a lender often results in wasted time. If a lead is not pre-approved, they might fall in love with a property that falls entirely out of their actual price range.
By addressing financing early in the relationship, you protect your schedule and help buyers understand their preliminary estimated budget before they become emotionally invested in a home.
How to Introduce Pre-Qualification Early
You do not need to act as a mortgage broker to introduce the concept of pre-qualification.
When a new lead inquires about a property, explain that understanding their estimated buying power is a necessary preliminary step. You can implement a pre-qualification platform that requires only their name, phone, and email, along with their explicit authorization to proceed.
This process initiates a soft credit inquiry, which does not affect the buyer's credit score. Using QLFI, the pre-qualification processing returns in 1.8 seconds or less.
Verify Buyer Buying Power Early
See how to integrate a digital pre-qualification step into your lead capture process without adding unnecessary friction.
Automating the Process with Digital Sign-In Pages
For open house events, screening leads directly at the door is an effective strategy.
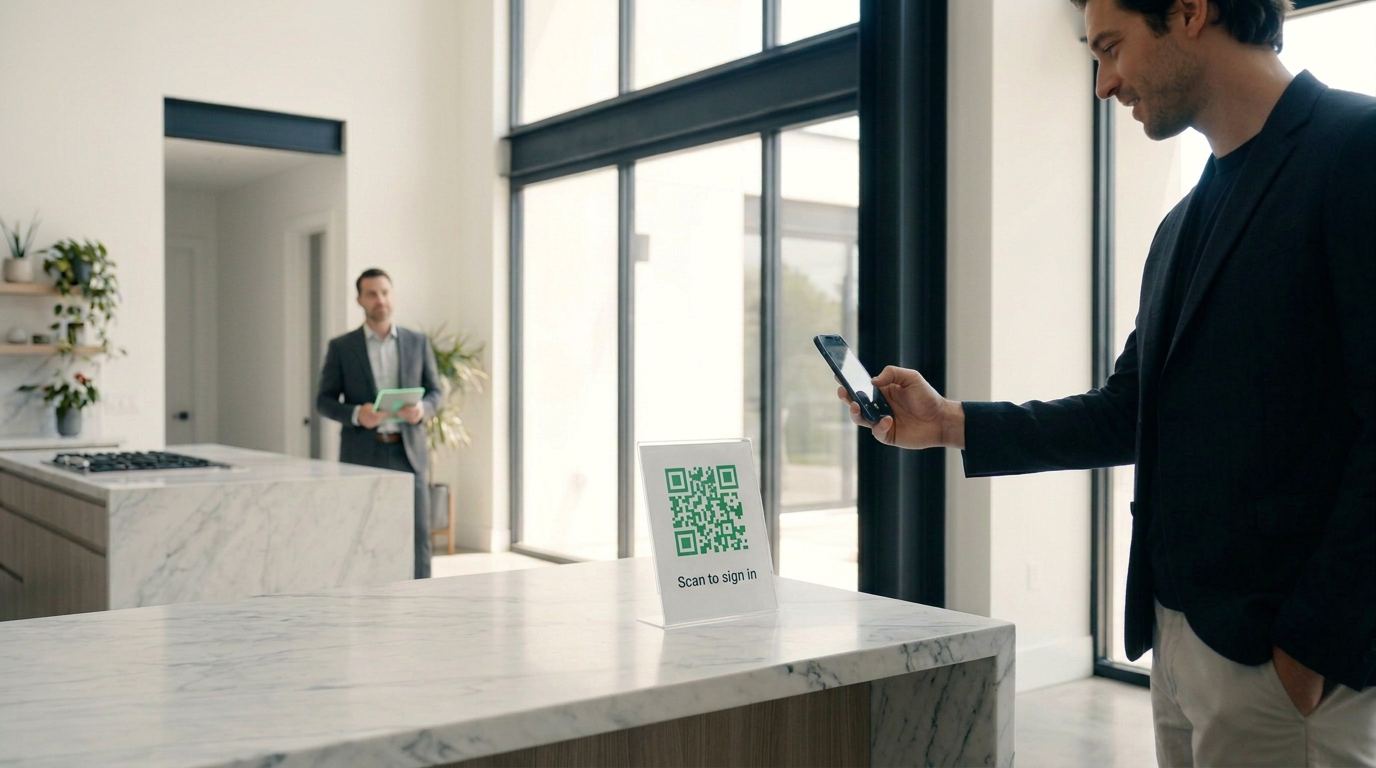
Using a digital sign-in page, agents can capture contact information and credit authorization before the tour begins. This separates casual attendees from serious prospects.
QLFI's Single Agent subscription costs $97 per month plus $5 per run, and it includes the Open House App with QR-code sign-in capabilities. If QLFI cannot match a visitor, there is no charge for that run.
Hypothetical example: Single Agent Monthly Volume
Calculating the monthly cost for a solo agent evaluating a steady stream of leads.
An agent captures and processes 40 authorized runs in a single billing month using the Single Agent plan.
Outcome: For example, processing 40 authorized runs in a month on the Single Agent plan results in a total cost of $297.
Choosing How to Handle Unverified Leads
Request digital pre-qualification before touring
- • The buyer is eager to view homes immediately
- • They have not yet spoken to a lender
Protecting the agent's time while rapidly advancing the buyer's journey
Host an initial consultation in the office
- • The buyer is hesitant to authorize an inquiry digitally
- • They require more education about the overall buying process
Traditional relationship-building without committing to unpaid property tours
Direct them to a public open house
- • The buyer refuses to provide basic information or authorization
Allowing property access without dedicating private showing time
Refusal to authorize a preliminary inquiry does not automatically mean a buyer is unqualified; they may simply prefer to work directly with their own chosen lender.
Frequently asked questions
Yes, real estate agents can establish business standards requiring preliminary estimates or formal lender pre-approval before scheduling private tours, provided these requirements are applied consistently to all potential clients.
No, QLFI requires only the buyer's name, phone, email, and explicit authorization to begin the soft credit inquiry process.
If a digital pre-qualification tool like QLFI cannot successfully match the visitor's identity, no preliminary estimate is generated. This is an unsuccessful match, not a credit denial, and you are not charged for that run.
Sources
- CFPB: Soft vs Hard Inquiries · CFPB